

Three different analyses of the UK’s economic problems were on show at the LSE last night in a panel organised by Neil Lee, author of Innovation for the Masses.
For Stan Boland, the starting point was the UK’s lack of large technology companies, along with the economic and strategic benefits that they bring. The veteran of several successful semiconductor start-ups, from ARM onwards, identified a shortage of capital as the key problem. Lacking the funding to dominate their niche, British start-ups sell out to better-funded US rivals or move to the US in search of capital. His proposed solution is for the government to inject billions more into venture capital, potentially at the expense of R&D tax breaks or Innovate UK grants. The goal should be a scene in the UK resembling that in New York or Boston where start-ups scale up and stay.
By contrast, Robyn Klingler-Vidra emphasised the strong firms we do have. The Kings College economist has recently been studying start-up culture in South Korea where, unlike the US, the goal is not to conquer the world with your start-up. The goal is to get bought by Samsung or another firm attached to one of the big chaebol conglomerates. In a sense, the result is the same as in the US – very large amounts of capital are mobilised behind good ideas – but it is achieved through the quite different mechanism of national champions. She thinks the UK could have more success if it more straightforwardly embraced national champions such as BAe Systems in the industrial strategy (now promised later this month).*
Put these two approaches together and you can start to see the legacy of 40 years of neoliberalism in the UK. One of neoliberalism’s strongest impulses is the destruction of state power because it is through the state that the people can secure a basic standard of living, for example through socialised healthcare, that insulates them from the market. Hence the drive to minimise public services and privatise them. Hence also the preference for gold and crypto-currencies – anything that deprives the state of the leverage that comes with a fiat currency. And hence the deep antipathy of neoliberals to national champions, for a national champion is a two-way street – the state supports the company but the company also relies on the state, which thereby expands its influence.
One of the concrete effects of four decades of neoliberalism is that the UK has few national champions left. With rules on takeovers relaxed, most of them have been split up, sold to overseas buyers and their UK operations run down, the ICI of 1979 being a prime example. Even those we retain often seem compromised – BAe Systems stopped calling itself British Aerospace when it decided to embed itself deeper in the US; Airbus is as much a French, German or Spanish company as it is a British one; ARM, although very much a British operation, is owned by a Japanese company and listed in the US.
So we simply don’t have the national champions that would allow a South Korean strategy to deliver wholesale benefits across the economy as a whole. And we don’t have the private capital that would allow us to pursue a US strategy. The neoliberalism of Thatcher, Blair and Cameron (not to mention Johnson, Sunak and Farage) has dumped us with the worst of all worlds.
The difficulty of the UK’s situation becomes clearer when we look at what seemed to be a bright spot – fintech. Wise, a London start-up valued most recently at $45 billion, is moving to the US for its listing on a stock exchange and there are worries that an even bigger fish, Revolut, may follow suit. The capital bit of capitalism in Britain is looking increasingly broken.
And so to the third speaker, Kanishka Narayan, long-time tech thinker and newly minted Labour MP for the Vale of Glamorgan. Unlike the previous two speakers, Narayan does not think there is a shortage of capital for scale-ups and he’s therefore not in favour of the government making more of it available.
Like Boland, I disagree with him on this, as it seems does the Treasury. In the Spending Review last week, when departments and agencies across the board got substantially less money than they asked for, the British Business Bank got more than it asked for, allowing it to make the first steps in Boland’s direction.
I found myself cycling home working through a counter-factual thought experiment: “What if Narayan is right?” If a shortage of capital is not at the root of the UK’s long decline in technology-based industries, what other levers can we pull to fix the problem? If Boland’s variant on the US model is shut to us, is there any alternative to pursuing something more like the South Korean or French model, to the state putting together the national champions that can provide the bedrock for the UK economy in an era of supply chain warfare?
In 1994, with Communism defeated and neoliberals in the ascendancy on both sides of the Atlantic, The Economist argued it was “Too late for national champions”. Perhaps it was instead too early.
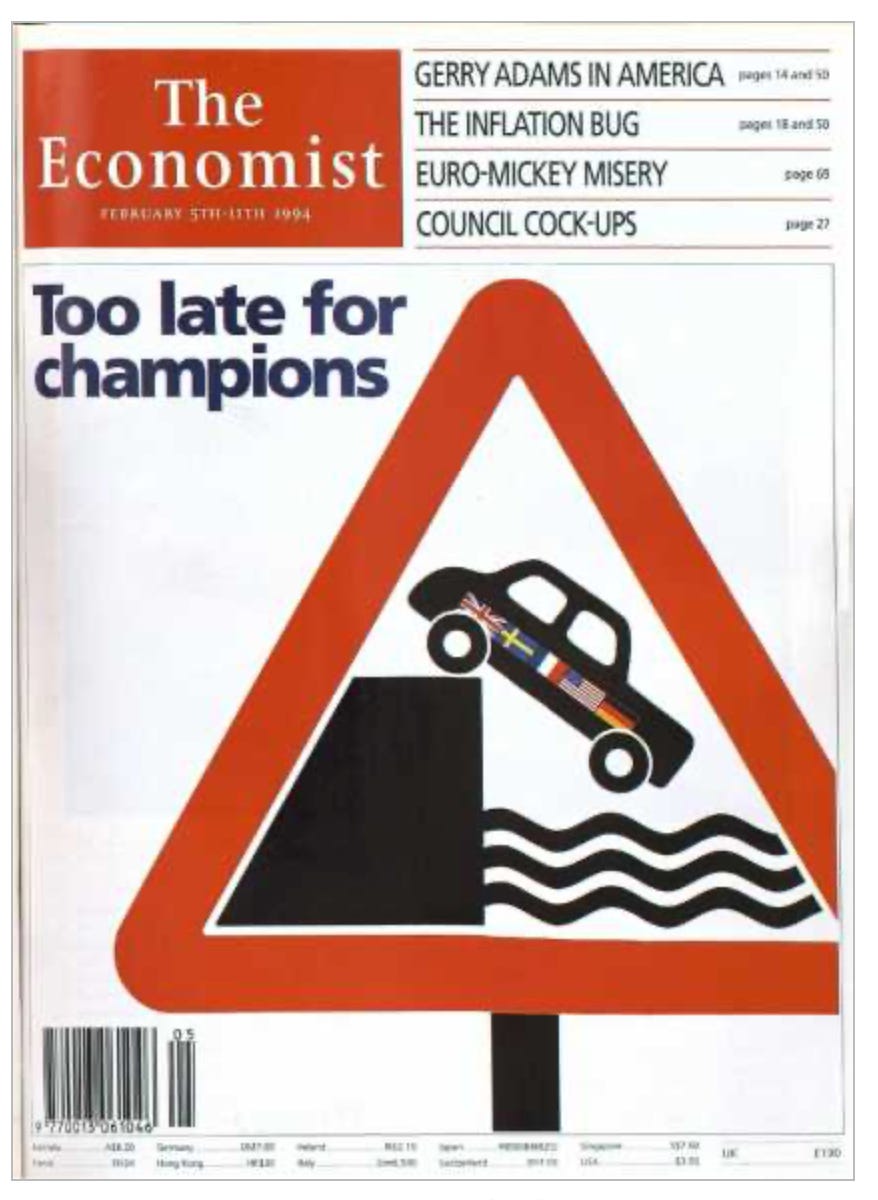
* Robyn dropped me a line after publication to say her idea of national champions that can benefit from the injection of startup ideas and talent is wider than readers may gather from my write up, including industrial leaders across sectors, including aerospace, automotive, shipbuilding, etc. See her piece in Foreign Affairs for more detail.
I studied economics 60 years ago when inflation and deflation were considered the top problems of Britain. Incomes policy and rampant left wing unionism competed to finally bring about the “winter of discontent” and Thatcher’s cure of reducing the money supply. Britain lost 40% of its heavy industries during the 1979-83 period and three million unemployed roamed the streets. Since then the financial services industry saw people like Rishi Sunak and others make millions as non-doms without any effect on the status of the UK as a major economy. We desperately need our start-ups to be able to grow in the UK without the risk of the Americans stepping in and buying them up. The problem, as ever, is funding. I bought £500 of BAe when it floated in the early 1980’s and am relieved that it survived but it certainly failed to live up to its hype at the time. We need some form of government insurance policy to enable startups to raise funds before they become profitable. Rachel Reeves is correct in desiring insurance and pension funds to invest at least 10% of their capital in British companies. The problem with America is that the rich are too rich and believe they own the country. Britain is a long way from that but a wealth tax on assets over £10 million would releave the pressure on the Treasury to provide funds for enterprises seen to build a stronger backbone for the economy as a whole.